Fuel economics will shape shipping’s transition
Shipping’s fuel transition will hinge on economics, regulation and decisions made before 2050
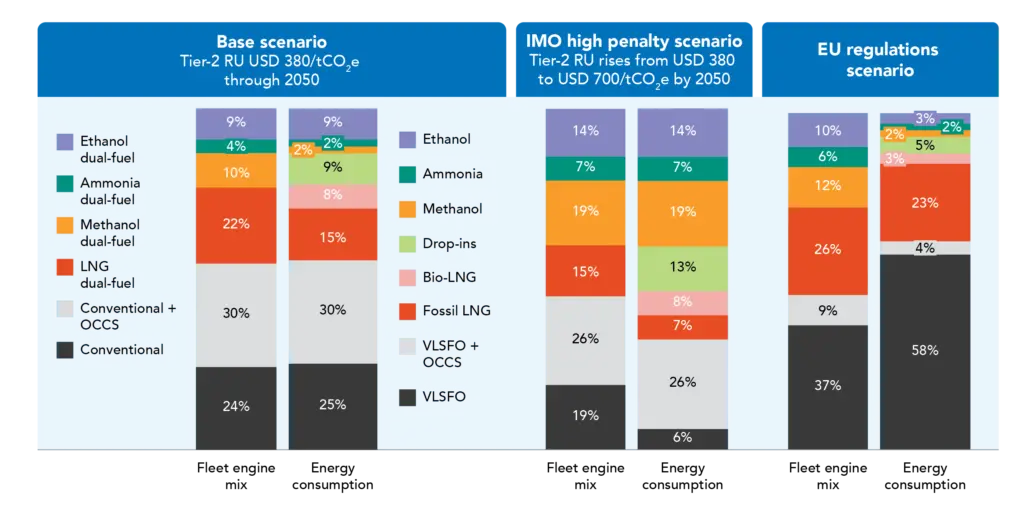
A new data model from Global Centre for Maritime Decarbonisation (GCMD) and Boston Consulting Group (BCG) shows that the availability of alternative-fuel engines will not necessarily translate into widespread use of those fuels, with fuel economics and regulation expected to play a decisive role in shipping’s transition.
Vessels typically operate for 25–30 years, while only about 4% of the global fleet is renewed annually. As a result, newbuild decisions made over the next decade are expected to establish much of the engine capacity available in 2050.
“Many vessels ordered over the coming decade will still be operating in 2050,” said Lynn Loo, chief executive of the GCMD. “Shipowners are therefore making long-lived engine choices before the relative economics of future fuels are clear.”
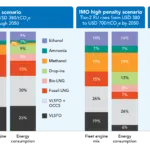
Dual-fuel capability gives shipowners flexibility to continue using conventional fuels when they remain cheaper. In the model’s base scenario, with the IMO Net-Zero Framework’s Tier-2 penalty held at US$380 per tonne of CO2 equivalent through 2050, methanol dual-fuel engines account for around 10% of fleet engine capacity, but methanol supplies only about 2% of fleet energy consumption.
The picture changes significantly when the carbon penalty rises. At US$700/tCO2e by 2050, new fuels, including drop-in fuels, reach approximately 61% of fleet energy consumption in the model.
The analysis also finds no clear cost winner between e-methanol and e-ammonia. While ammonia benefits from lower production costs, additional logistics and safety requirements largely offset that advantage.
Future fuel competitiveness will remain sensitive to green hydrogen costs, biogenic CO2 prices, bio-methanol costs and biofuel regulation. Those uncertainties could significantly influence both vessel choices and the development of future bunkering hubs.
“The maritime fuel transition is being shaped as much by policy and cost uncertainty as by technology readiness,” said Anand Veeraraghavan, managing director and senior partner at BCG.
Related Articles
 ALTERNATIVE FUELS & LUBRICANTS
 ALTERNATIVE FUELS & LUBRICANTS
 ALTERNATIVE FUELS & LUBRICANTS